Riggers Liability Insurance
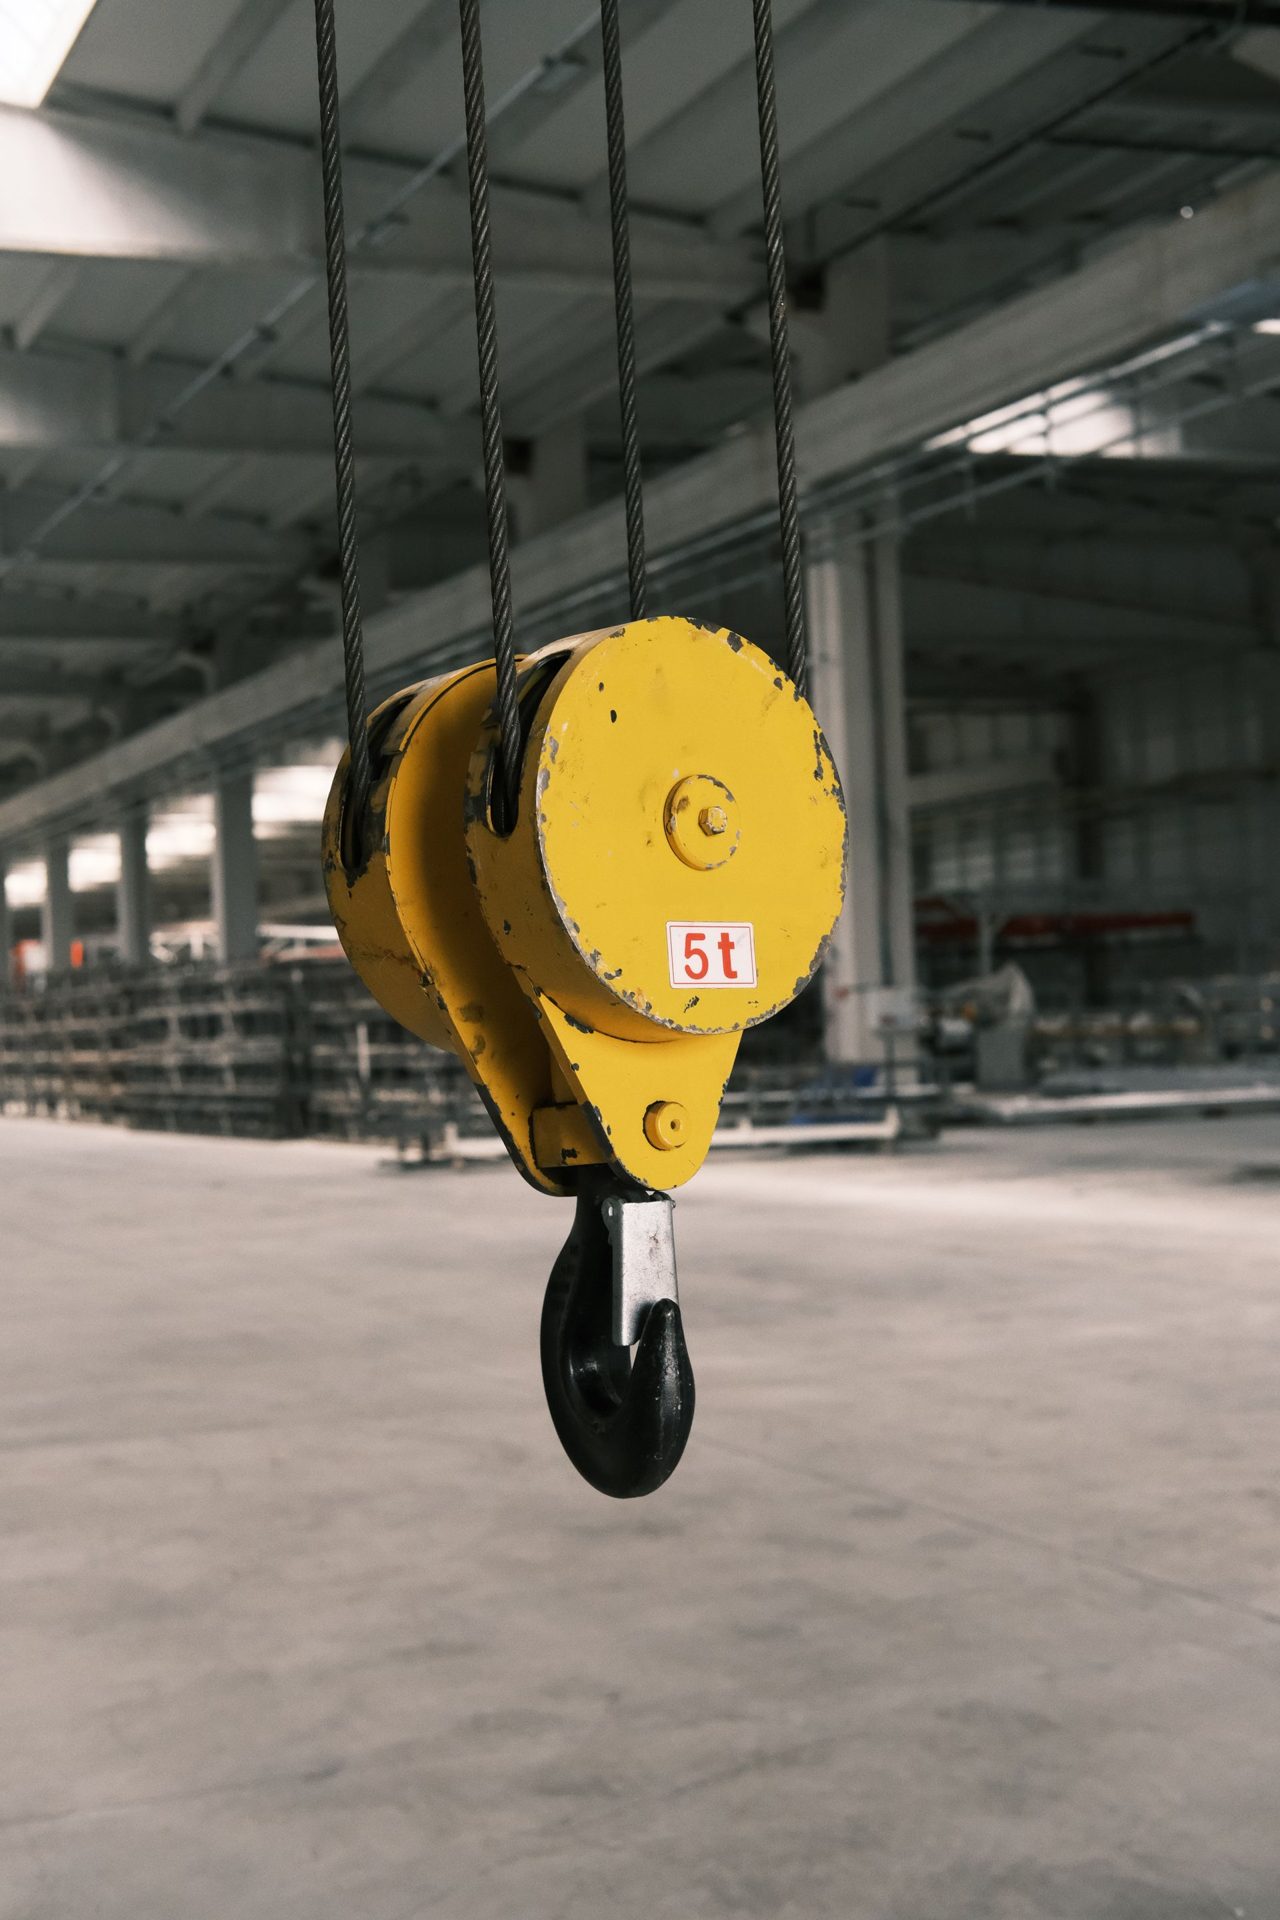
Pays for damage to the customer’s property while it’s on your hook, which GL usually won’t.
Can y’all handle it?
Yes sir.
- Riggers liability: pays when you’re legally liable for damage to the customer’s property while you lift or move it
- On-hook: may pay for damage to the load no matter who’s at fault
- Written as a GL add-on or on an inland marine form
New to the business?
Just getting started? That’s fine by us. We insure new contractors. No loss history? No problem. You’ll sign a No Known Loss letter and we’ll go from there.
Already insured and looking around?
Send us 3-5 years of loss runs and your current policy or dec pages. We’ll shop it around for you, with quicker COIs and calls returned.
How much down?
We offer premium finance.
How fast can I get a COI?
If you’re new with us, we’ll gather your info, fill out the application, get it quoted, and go over it with you. Most quotes take about 4 to 5 days. Some come back quicker and some take a little longer. Once you’re covered, you’ll get COIs the same business day you ask.
The policy wording decides what’s covered.
Frequently Asked Questions
What does riggers liability cover?
It’s built to cover damage to other people’s property while you’re lifting, rigging or moving it, subject to the policy and limits.
Is riggers liability the same as an installation floater?
No. An installation floater covers property you install that becomes part of the project.
Related pages
- /resources/does-general-liability-cover-property-being-lifted/
- /resources/crane-coverage-comparison-guide/
- /crane-general-liability/